

The ad tech and CTV worlds are still digesting the biggest news coming out of Cannes - Walmart snatching up Vibe for $1.4 billion.
It seemed a signal that CTV advertising is set to become far more democratic and dynamic -and the long-promised influx of SMBs and DTC brands into TV was finally arriving.
But with Vibe, is Walmart going to be limited to targeting second tier TV inventory?
Put another way - are the major TV players destined to keep “programmatic TV” at arm’s length?
The reason I ask is that I happened to be recording a podcast on the ground at Cannes with execs from Paramount and Tatari just after the Vibe news. We were talking about Tatari’s recent deal with a slew of media companies aimed at making it easier to buy ads directly - and how maybe some TV ad space should always remain available to the few.

“Not every streaming experience should be bought the same way,” said Leo O’Connor EVP Streaming, Paramount Advertising, on this week’s episode of Next in Media. “Someone watching a library episode, someone watching the nightly news, someone tuning into a massive sporting event, or millions of viewers watching a season premiere simultaneously—those are completely different viewing experiences.”
Paramount’s position is noteworthy - given that so much has been made of this idea that everything is on the table these days in TV ad land. You can log into any number of self-serve platforms, and get your ad right into the Olympics, or an NFL game, theoretically.
Yet is that not really the case? Interestingly, even Amazon - the ultimate example of advertising and an individual seller open marketplace - has been hesitant to carve up Thursday Night Football or NBA playoff games to thousands of different advertisers.
“Breaking a huge cultural viewing moment into millions of individual impressions isn’t always the smartest approach,” said O’Connor. “Some environments are perfect for programmatic buying. Others are better suited for more direct transactional models.”
“Our goal is to match the buying method to the content experience.”
In the case of Tatari, that means making direct transactions much smoother. The company even poked at the concept of wide open TV marketplaces with a provocative billboard in Cannes depicting a group of DSPs on the sidelines when it comes to sports.
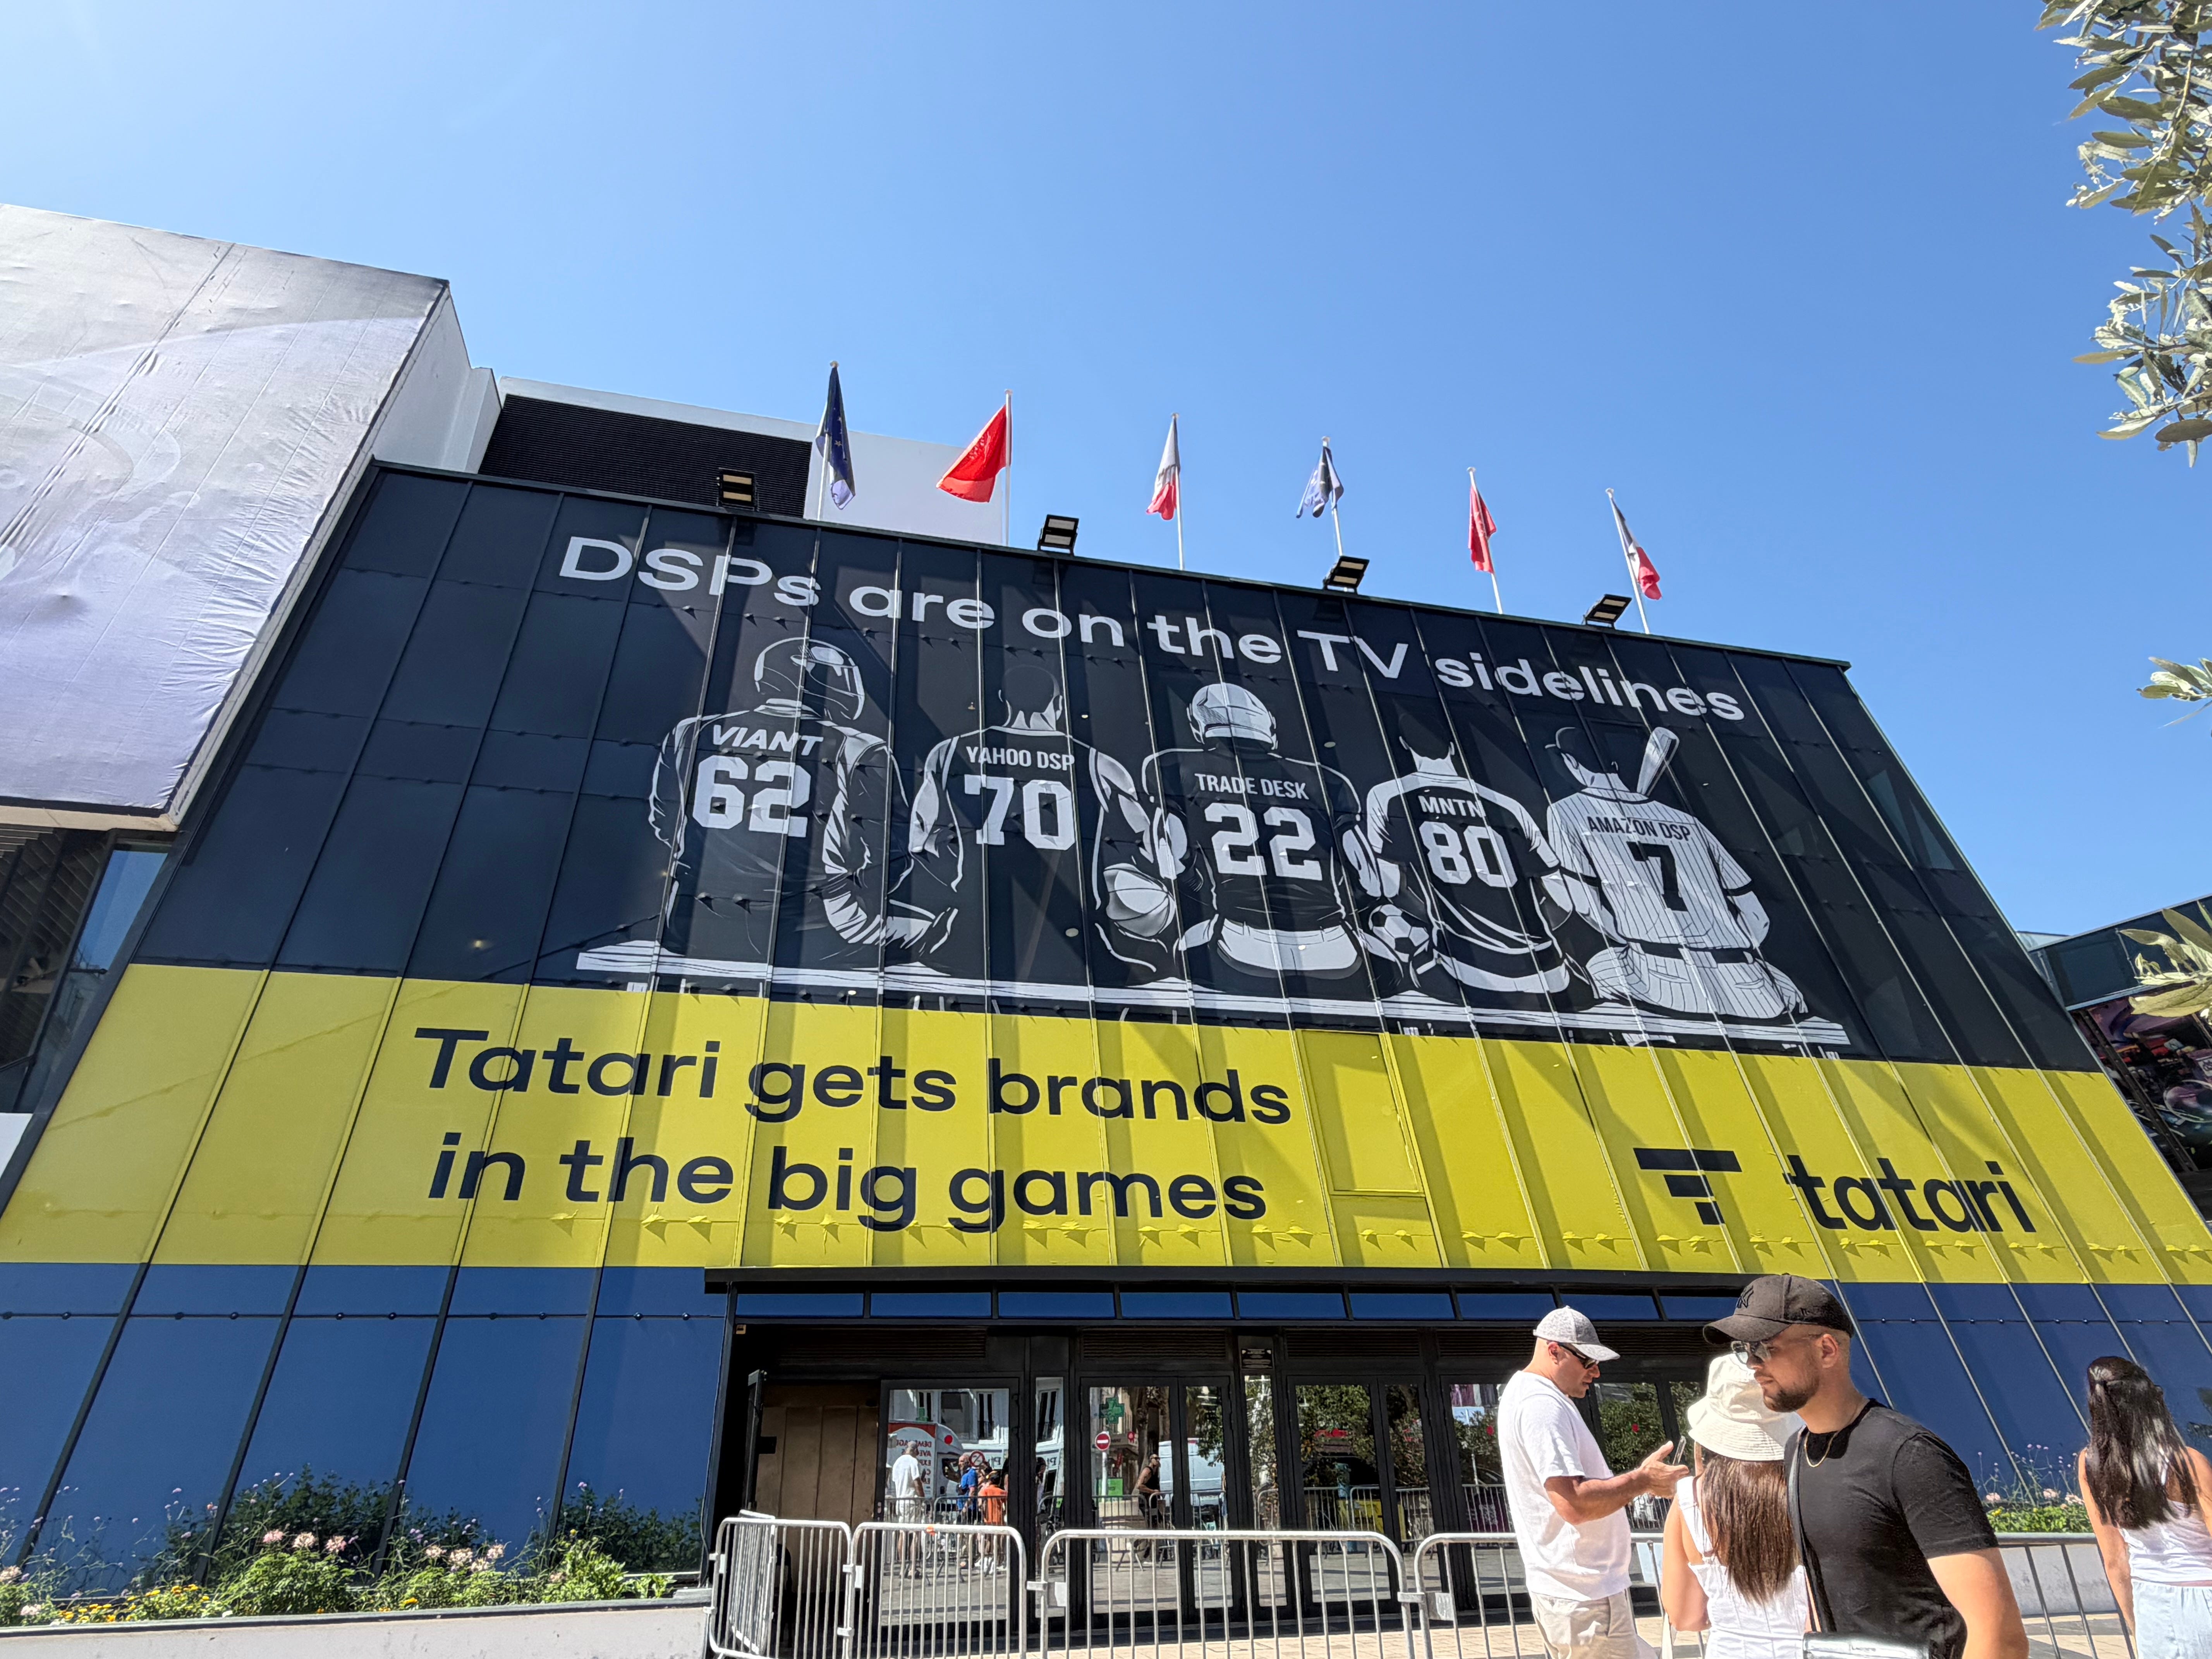
“The reality is that the most premium television inventory—live sports, major tentpole programming, sponsorship opportunities—often isn’t available through traditional programmatic pipes,” said Tatari CEO Philip Inghelbrecht. “So if a brand only buys TV programmatically, it may never have access to the moments it actually came to television for in the first place.”
So does that mean that TV advertising is becoming a two-tiered system? And that Walmart will be slightly handcuffed with Vibe? Will other self-serve platforms be excluded from some of the ‘good stuff’?
Well, it sort of depends on how you define programmatic TV.
“It’s not true that premium inventory is only available through guaranteed deals,” said MNTN CEO Mark Douglas. “But you do have to have unique deals with the streaming networks.”
For instance, Douglas said that over the past few quarters, MNTN has been able to bring a unique set of mid-sized advertisers into ads running during March Madness, Peacock’s reality smash “Love Island,” and even the World Cup this week thanks to pre-negotiated integrations with top media companies. But not any local pizza joint with a credit card could do the same. “There can’t just be an open auction. And the big networks need to manage channel conflict.”
Of course, you can make a strong argument that smaller brands or DTC marketers actually don’t need to be blasting ads during costly live events like the World Cup or the premiere of something like “The Bear,” where the costs and ROI could be punitive. There is so much more CTV ad inventory becoming available where CPMs are sinking (just ask the FAST space).
However, at the same time, the tech platform are moving much faster than traditional media companies on this front. YouTube by nature is open to a wider swath of advertisers. And judging by the cheap local ad I saw repeatedly during a binge of Amazon’s “Jury Duty - Season 2” (excellent btw), Amazon won’t be shy about selling to smaller brands (as long as they use Amazon’s DSP). It may just depend on the situation.
Douglas said that for more small brands to become comfortable on TV, they’ll need more mechanisms to track performance. And many direct deals (programmatic guarantees) “are built for reach and frequency,” he said. “They are limited in that you have to talk to people, and they don’t have the same data inputs and layers of measurement” than you would find in display advertising or social platforms.
In the meantime, TV companies will exercise a level of caution. “Automation will continue expanding wherever it makes sense, but brands still value those collective audience moments.” said 'O’Connor. “There’s room for personalization—maybe the creative changes slightly by geography or audience—but advertisers still want to know they’re appearing during the biggest shows and sporting events.
“The best results come from combining broad reach during premium moments with precise one-to-one targeting afterward.”
Great analysis, Mike. One thing I'd add is that the conversation shouldn't stop at how premium inventory is bought, but also how it's validated.
As buyers gain access to more premium CTV environments through different transaction models, independent verification of traffic quality and delivery becomes increasingly important. Premium inventory delivers its full value only when advertisers have confidence in what's actually being delivered.